
The Amount Is Small. The Habit Is the Whole Fortune.
Every investing book opens with a story about someone who started with almost nothing, which tells you the authors know exactly what their readers are thinking: that investing is a rich person’s game played with sums they do not have. It is not. What compounding rewards is not the size of the deposit but the length of time it stays invested and the regularity with which it is joined by the next one — which means a modest salary invested monthly from age twenty-five will, under ordinary market returns, finish ahead of a large salary invested in a panic of catching up at forty-five. Learning how to start investing on a small salary is therefore less a finance problem than a sequence problem: get the order of operations right (defence before growth, matching before markets, boring before clever), automate the smallest sustainable amount, and let decades do the heavy lifting that your pay cheque cannot. This guide walks the sequence in full: the starter safety net that keeps investing from becoming gambling, the free money to collect before buying anything, the one default investment that suits most beginners and why the industry prefers you not to notice, and the behavioural settings — automation, fee awareness, and a plan for the first crash — that decide whether the habit survives contact with real life. It builds directly on our guide to personal finance habits that quietly build wealth over time, and pairs with our guide to how to choose a password manager — because money and accounts deserve the same treatment: a system set up once, properly, that protects you without daily effort.
Step One and Two: The Safety Net and the Free Money
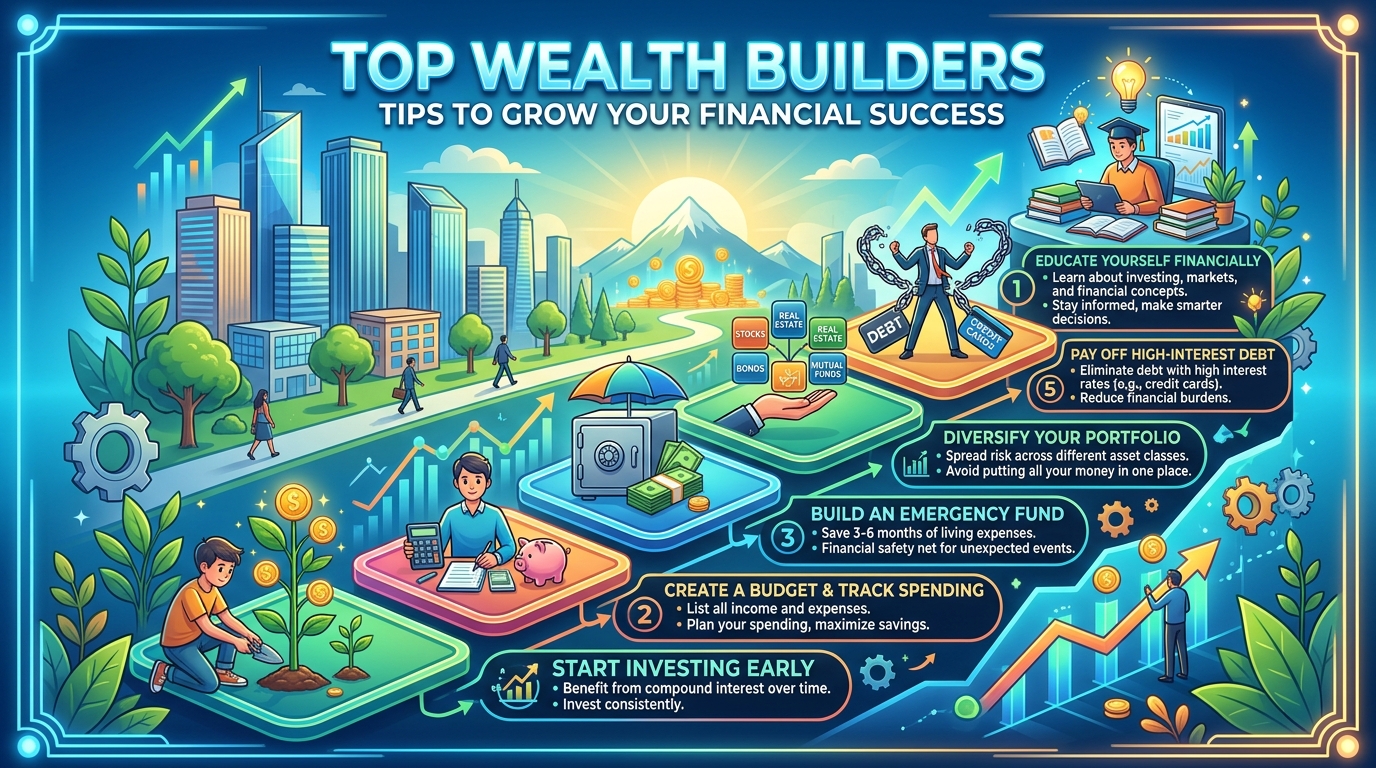
Investing begins with not investing. Before any fund purchase, build a starter emergency fund of one month’s essential expenses in an ordinary savings account — small enough to reach quickly, large enough that a broken phone or a lost shift does not force you to sell investments (or borrow at credit-card rates) at the worst moment; grow it toward three months over time as the investing habit runs beside it. Debt triage belongs in the same breath: high-interest debt, especially cards charging twenty percent or more, is a guaranteed negative return that no beginner portfolio can outrun, so clear that first — the only common exception being the employer pension match, which brings us to step two. If your employer matches pension or retirement contributions, contribute enough to collect the full match before anything else in this article. A match is an instant, risk-free doubling of that slice of money — a 100 percent return before the market moves at all — and declining it is volunteering for a pay cut. Only after the starter fund exists and the match is captured does the first actual investment make sense, and by then the monthly amount has usually revealed itself: whatever is left when the essentials, the debt payments, and a life worth living are funded — ten percent of take-home is a strong target, five is a fine start, and a fixed modest sum you will actually sustain beats an ambitious one you will abandon in month three every single time.
Step Three: The Boring Default That Beats Most Stock Pickers
For the overwhelming majority of beginners, the evidence supports one default holding: a broad, low-cost index fund — a single fund that owns a slice of hundreds or thousands of companies at once (a national market index, or a global one for instant worldwide diversification), bought monthly and held for years. The reasons are structural, not fashionable. Diversification is automatic, so no single company’s disaster can wound you. Fees are minimal — often a tenth or less of an actively managed fund’s charge — and fees compound exactly like returns, in the opposite direction: a one-percent annual fee difference consumes a startling share of a lifetime portfolio. And the performance bar is brutal for the alternatives: over long periods, the majority of professional fund managers, paid fortunes to pick winners, fail to beat the plain index they are measured against — a fact that should calibrate any beginner’s confidence in their own stock tips, their colleague’s, or an influencer’s. Choose the wrapper your country rewards (tax-advantaged retirement and investment accounts first, in whatever local form they take), choose the broadest cheap fund available inside it, and set the contribution to leave your account the day after payday — because the automation is not a convenience feature, it is the strategy: money that never lands in your spending account is money you never have to decide about, and investing that depends on monthly motivation is investing that stops in the first expensive month.
Step Four: Surviving Your Own Behaviour
The final step is the one the brochures skip: your portfolio’s largest risk is you. Markets fall by a fifth or more every handful of years, and the beginner who sells in the first crash converts a temporary paper loss into a permanent real one — and usually buys back later, higher, having paid tuition for the lesson twice. Set the defences while calm. Match risk to horizon: money needed within three years (a deposit, a wedding) does not belong in shares at all; money for retirement decades away can ride the falls precisely because it has decades to recover. Automate and ignore: check the portfolio on a schedule — quarterly is plenty — because daily checking manufactures daily emotions, and the news will always supply a narrative for why this fall is the different one. Rebalance simply: if you hold more than one fund (shares and bonds, say), nudge the mix back to its target once a year, which mechanically sells a little of what rose and buys a little of what fell. Grow the contribution, not the complexity: each pay rise, raise the monthly amount by a share of the increase before lifestyle absorbs it — this single habit, contribution growth, will out-earn almost any fund-switching cleverness available to you. And hold the frame that started this guide: you are not trying to win the market this year. You are buying, month by month, at every price the decade offers, a diversified claim on the entire economy’s future — with a small salary, started now, sustained boringly. That is not the consolation prize version of investing. Done for thirty years, it is simply what investing is.