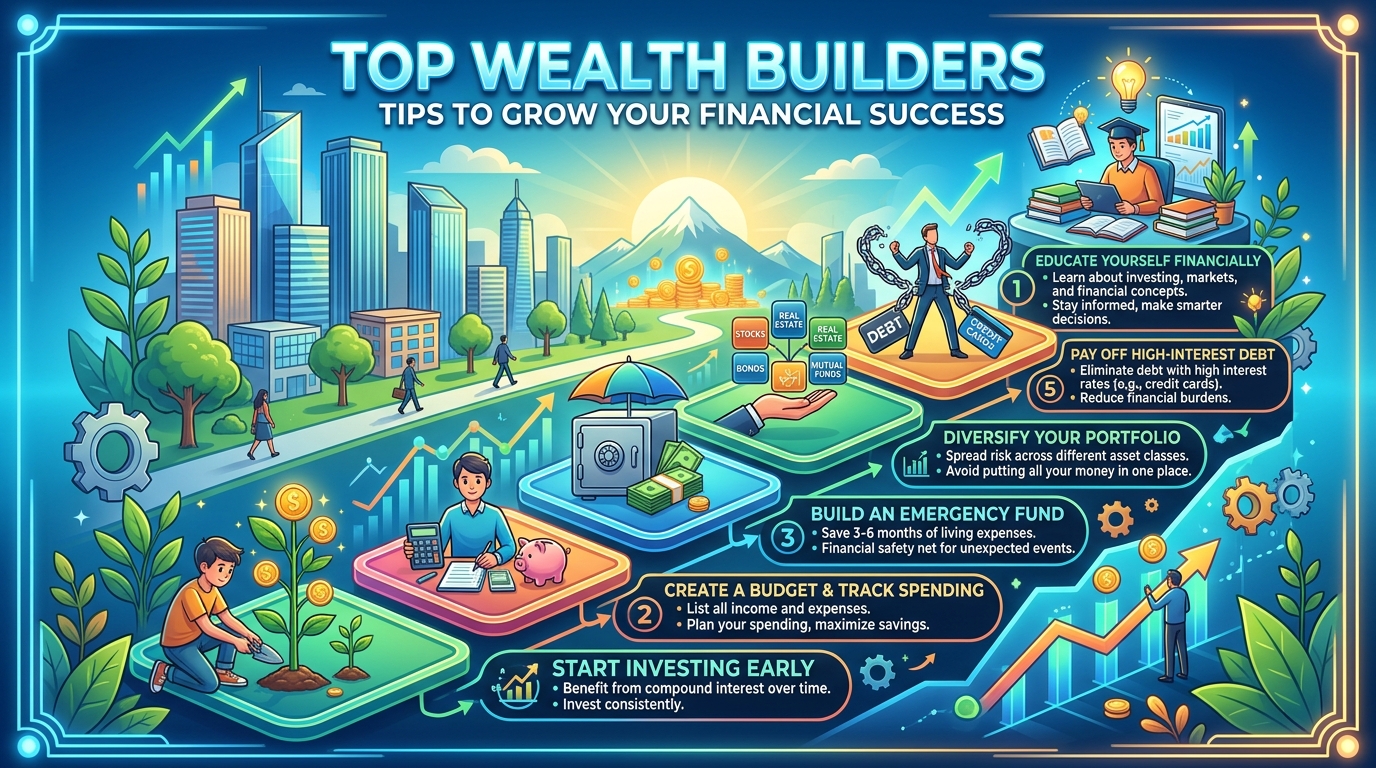

 Wealth rarely arrives in a single dramatic moment. For most people it accumulates quietly, in the gap between what they earn and what they spend, repeated over many years. That is why personal finance habits matter more than financial knowledge. Plenty of people know what they should do with money; the ones who actually build wealth are those who turned the right behaviours into routines that run almost automatically. This guide covers the habits that do the heavy lifting, none of which require a finance degree, a huge salary or heroic willpower.
Pay Yourself First, Automatically
The oldest and most reliable of all personal finance habits is paying yourself first. Before money can leak into shopping, subscriptions and spontaneous treats, a fixed amount moves to savings or investments on payday itself. Automate the transfer so the decision happens once, not every month under pressure. What remains in your current account becomes, by design, safe to spend.
Start smaller than you think is worthwhile if necessary. A modest automatic amount that survives every month beats an ambitious one you cancel by March. Then raise it gradually — a little with every pay rise — before lifestyle has a chance to absorb the increase. Within a couple of years, most people are saving sums they would once have sworn were impossible on their salary, and they genuinely do not miss the money, because they never saw it as spendable in the first place.
Track Spending Honestly — Briefly, but Regularly
You cannot change what you do not see. Tracking spending has a reputation for misery because people attempt it in punishing detail. The effective version is lighter: one short review each week or month, looking at where the money actually went, grouped into rough categories. The goal is not guilt; it is pattern recognition. Almost everyone finds one or two surprises: the takeaway total, the subscriptions quietly renewing, the convenience spending that adds up to a holiday.
Ask the question that unlocks most money problems: where does it actually go? As with any kind of troubleshooting, a good problem solver starts with the right question, and in personal finance that question is rarely “how do I earn more?” It is “what is this money supposed to do for me, and is it doing it?” Align spending with your honest answer and cuts stop feeling like sacrifice, because you are funding what you value by defunding what you do not.
Defeat Lifestyle Creep and Costly Mistakes
The quiet enemy of wealth is lifestyle creep: every income increase matched by an equal increase in spending, so the gap never grows. Fight it with a simple rule — when income rises, let savings rise first and lifestyle rise second, by less. Enjoy improvements deliberately and slowly, and you will appreciate each one more while keeping the habit that actually builds security.
Protecting wealth also means avoiding large, dumb losses. Keep an emergency fund so a broken boiler or a lost contract never becomes expensive debt. Be deeply suspicious of anything promising fast returns, and of buying health or financial products online without proper guidance — the market for miracle products is ruthless, which is why sensible guidance on topics like buying steroids online stresses legal rules, medical advice and safety before purchase. The same caution applies everywhere money leaves your account quickly: slow down, verify, and consult a professional when the stakes are high.
Invest Steadily and Let Time Do the Work
Saving protects money; investing grows it. The habits that matter here are boring on purpose: invest regularly rather than trying to time the market, diversify rather than betting on one exciting story, keep costs low, and leave the money alone for years so compounding can work. Market falls are the price of admission for long-term returns, and the investors who suffer most are usually those who panic and sell at the bottom.
Match investments to your timeline and temperament. Money needed within two years belongs somewhere safe and accessible; money for a goal a decade away can ride out market weather. If choosing investments feels overwhelming, that is a sign to learn the basics properly or take regulated advice, not a sign to gamble on tips from the internet. Among personal finance habits, patience is the one with the highest interest rate.
Review, Insure and Plan the Boring Essentials
Finally, wealth needs housekeeping. Review your accounts, pensions, insurance and beneficiaries once a year. Check that old workplace pensions are not forgotten, that insurance still matches your life, and that your will and essential documents reflect reality. These tasks are unglamorous, which is precisely why they get neglected until they become emergencies.
Build these habits into a simple annual rhythm and they stop feeling like chores. Automate the saving, skim-review the spending, invest on schedule, protect against catastrophe and tidy the paperwork once a year. None of it is exciting, and all of it works. Wealth built this way does not depend on luck, timing or genius. It depends on the same thing as fitness, fluency or any other long-term achievement: ordinary personal finance habits, practised quietly, for a very long time.
It also pays to teach these habits onward. Households where money is discussed calmly and honestly raise children who treat saving as normal rather than as a mysterious adult anxiety. You do not need formal lessons; you need visible behaviour — the budget talked through at the kitchen table, the purchase deliberately delayed, the savings goal pinned to the fridge and celebrated when reached. Money habits, like manners, are caught more than they are taught, and your routine is somebody else’s first financial education.
Conclusion
There is no secret trick behind most people’s financial security. There is a set of personal finance habits — pay yourself first, watch where money goes, resist lifestyle creep, invest steadily and keep the essentials in order — repeated month after month until they feel like personality rather than effort. Start with one habit this payday. In ten years you will not remember the purchases you skipped, but you will be very glad you kept the gap between earning and spending, and let it grow.